As financial institutions close out the quarter, executive discussions inevitably center on portfolio performance, risk mitigation, and strategic forecast adjustments. Boardrooms want to know exactly how current origination cohorts are seasoning, where the portfolio is exposed to macroeconomic pressure, and how to fine-tune origination guidelines to protect future margins.
Many risk teams approach these boardroom reviews heavily disadvantaged. They rely on lagging indicators like a simple, aggregate 30-60-90-day delinquency report to assess credit health.
The problem with aggregate metrics is that they tell you what is happening across your entire portfolio today but obscure when and why performance began to drift. If your overall delinquency rate rises by 50 basis points, is it because a macroeconomic event affected all borrowers equally, or because an underwriting adjustment made six months ago is beginning to underperform?
To find those answers, credit risk teams need real-time portfolio intelligence that shows where risk is emerging and how today’s lending decisions will affect tomorrow’s performance. That means looking beyond surface-level metrics and analyzing portfolio performance at a much more granular level. The analysis is well understood. What holds most teams back is the architecture of the underlying loan servicing platform.
Portfolio Intelligence Starts with Cohort Analysis
One of the most effective tools for generating portfolio intelligence is cohort or vintage analysis. In loan portfolio management, a vintage groups a cohort of loans by the month, quarter, or year they originated.
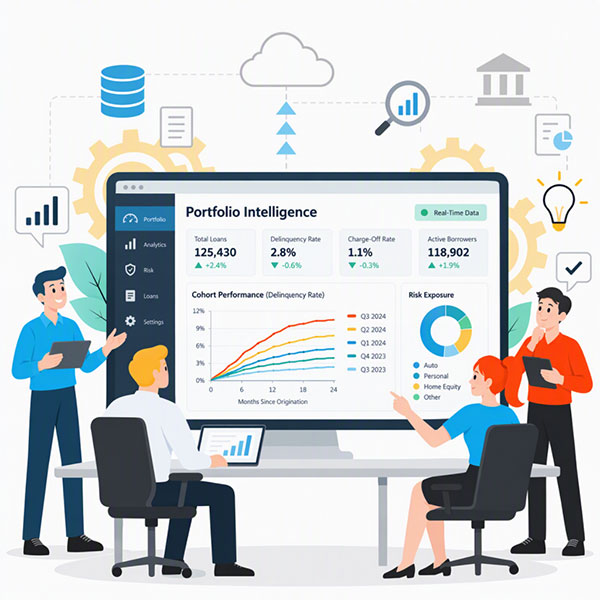
Vintage analysis tracks cumulative loss, default, and delinquency curves, along with roll rates, as specific loan cohorts age throughout their lifecycle. Instead of viewing the portfolio as a single pool of loans, lenders can evaluate multiple cohorts side by side to understand how credit performance evolves over time.
When these cohort performance curves are layered together, meaningful patterns emerge. If a Q3 origination cohort exhibits a significantly steeper loss trajectory at Month 6 than a Q1 cohort at the same stage of maturity, risk teams gain an early-warning signal long before losses become material enough to impact portfolio profitability.
This level of analysis enables lenders to identify emerging risks, validate underwriting decisions, and make proactive adjustments before performance issues become widespread. Vintage curves also support CECL lifetime-loss estimation, so the same analysis serves finance as well as risk.
Why Legacy Loan Servicing Systems Limit Portfolio Intelligence
While cohort analysis is invaluable for portfolio management, risk monitoring, and CECL compliance, generating these insights on a legacy loan servicing platform is often an operational challenge.
Traditional loan servicing systems function primarily as systems of record. Data is stored in isolated environments, updated through batch processing, and often disconnected from origination systems and analytics tools.
To build cohort performance reports, analysts frequently must extract large flat files from the loan servicing platform, pull historical origination data from a separate Loan Origination System, reconcile inconsistent data fields, remove duplicate records, and manually create complex spreadsheet models or database queries.
The result is a slow and resource-intensive process. By the time reports are cleaned, compiled, validated, and shared with leadership, the data may already be weeks old.
Stale reporting limits an institution’s ability to react quickly, forcing leadership teams to make decisions based on historical conditions instead of current portfolio realities.
Building Real-Time Portfolio Intelligence with Shaw Systems
True data strategy means moving beyond manual reporting and toward automated insight. At Shaw Systems, we designed our loan servicing and collections solutions to eliminate the traditional disconnect between back-office loan administration and forward-looking credit risk management.
Rather than functioning solely as an administrative platform, Shaw transforms loan servicing data into a continuous intelligence engine through several key capabilities:
A Single, Unified Data Foundation
Because Spectrum supports the full servicing lifecycle—from retail loan servicing through collections and recovery—every payment event, delinquency status change, modification, recovery, and charge-off is captured within a single system.
This creates a consistent source of truth across the organization and gives every team one set of definitions and data points to work from.
Open APIs and Bi-Directional Data Integration
Through an API-first architecture, Spectrum enables organizations to combine real-time loan servicing data with attributes from whichever origination system a lender already uses, along with external data sources. Spectrum fits alongside that origination platform, so credit teams keep their front-end tools and gain a clear view of how those loans perform once they are on the books.
Risk teams can segment performance not only by origination date but also by underwriting and portfolio characteristics such as:
- Credit score bands
- Loan-to-value ratios
- Origination channels
- Product types
- Geographic concentrations
This flexibility enables more precise analysis and a deeper understanding of the factors influencing portfolio performance.
Proactive Risk Identification
Instead of relying exclusively on historical reports, Spectrum lets lenders monitor borrower behavior as it occurs.
Integrated loan servicing and collection workflows provide visibility into payment trends, delinquency patterns, and emerging behavioral shifts, enabling risk teams to identify performance changes before they develop into significant loss events. Official regulatory and financial reporting continues to run through each institution’s own controls.
Closing the Loop: Loan Servicing as a Credit Policy Feedback Engine
This evolution in data accessibility fundamentally changes the strategic role of loan servicing within a financial institution.
When a loan servicing platform continuously feeds clean, real-time operational data into analytics environments, loan servicing becomes the most direct feedback mechanism for the institution’s broader credit strategy.
For example, if cohort analysis reveals that loans originated through a specific digital channel are experiencing elevated losses around Month 9, leadership can respond within the quarter instead of waiting for the annual portfolio review.
Credit teams can quickly refine underwriting criteria, adjust loan-to-value thresholds, modify pricing strategies, or introduce additional risk controls for that segment. The result is a more agile organization capable of responding to portfolio trends before they become portfolio problems.
The Shaw Systems Takeaway for the Boardroom
When evaluating technology investments, origination platforms rightly draw attention because they drive loan volume. Growth delivers its full value when lenders can also see how those loans perform and where risk is building, and that visibility lives in the servicing platform.
Modern loan servicing platforms play a critical role in helping lenders move beyond static reporting and toward real-time portfolio intelligence.
Upgrading to an enterprise, cloud-accessible loan servicing platform like Spectrum supports your customer service and collections teams and is also a foundational investment in your organization’s data strategy.
By turning raw payment and loan servicing data into clear, actionable portfolio intelligence, Shaw gives executive teams the visibility needed to navigate risk confidently, respond to changing market conditions faster, and scale their portfolios more profitably.
Want to see what live cohort views look like on your own portfolio? Reach out and we’ll walk you through it.
Get news from Shaw Systems Associates, LLC in your inbox.